Crypto, Stablecoins, Bitcoin & Blockchain Money Transfers
“I think we will know when bitcoin has reached prime time when it is transferring more value each day than Western Union or Money Gram…”
Roger Ver, November 2013
Taxonomy:
- Crypto-native transfer: crypto at both ends.
- Stablecoin sandwich: fiat → stablecoin → fiat.
- Digital-dollar access: buying or holding stablecoins without transferring them internationally.
- Consumer remittance: an individual sends money to another individual.
- Business payment or treasury: companies move working capital, supplier payments, or FX liquidity.
- Wholesale settlement: regulated institutions settle obligations between themselves.
- Blockchain infrastructure: the ledger or messaging layer, regardless of the currency transferred.
Since the publication of “Bitcoin: A Peer-to-Peer Electronic Cash System” in 2008, international money transfers, although constituting a smaller portion of cross-border payments, have emerged as one of the most promising use cases for crypto.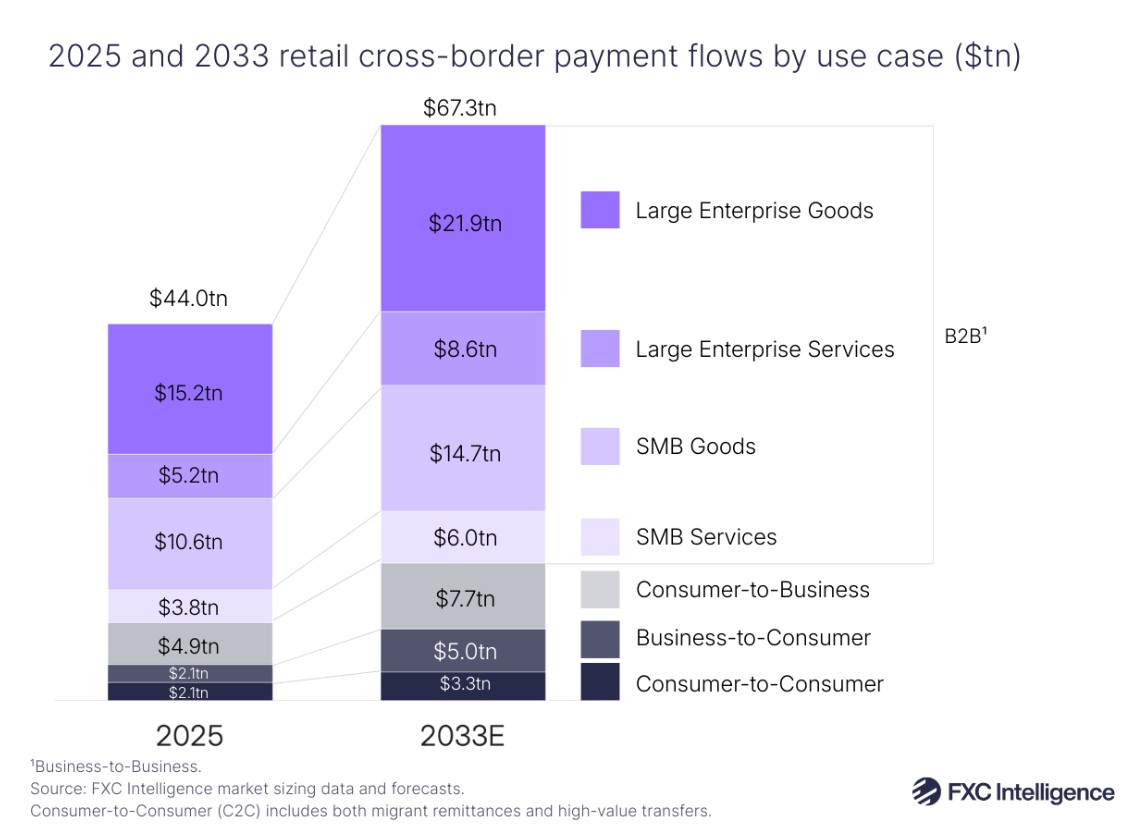
The original thesis was simple: remittance users paid high prices for slow, opaque service, while blockchain could move value almost instantly at negligible rail cost. Crypto founders and investors also framed it as a way to bypass banks and reach underserved recipients. Startups raised capital to test that thesis through consumer services and MTO partnerships. El Salvador later turned it into a national experiment by making Bitcoin legal tender and promoting it for remittances.
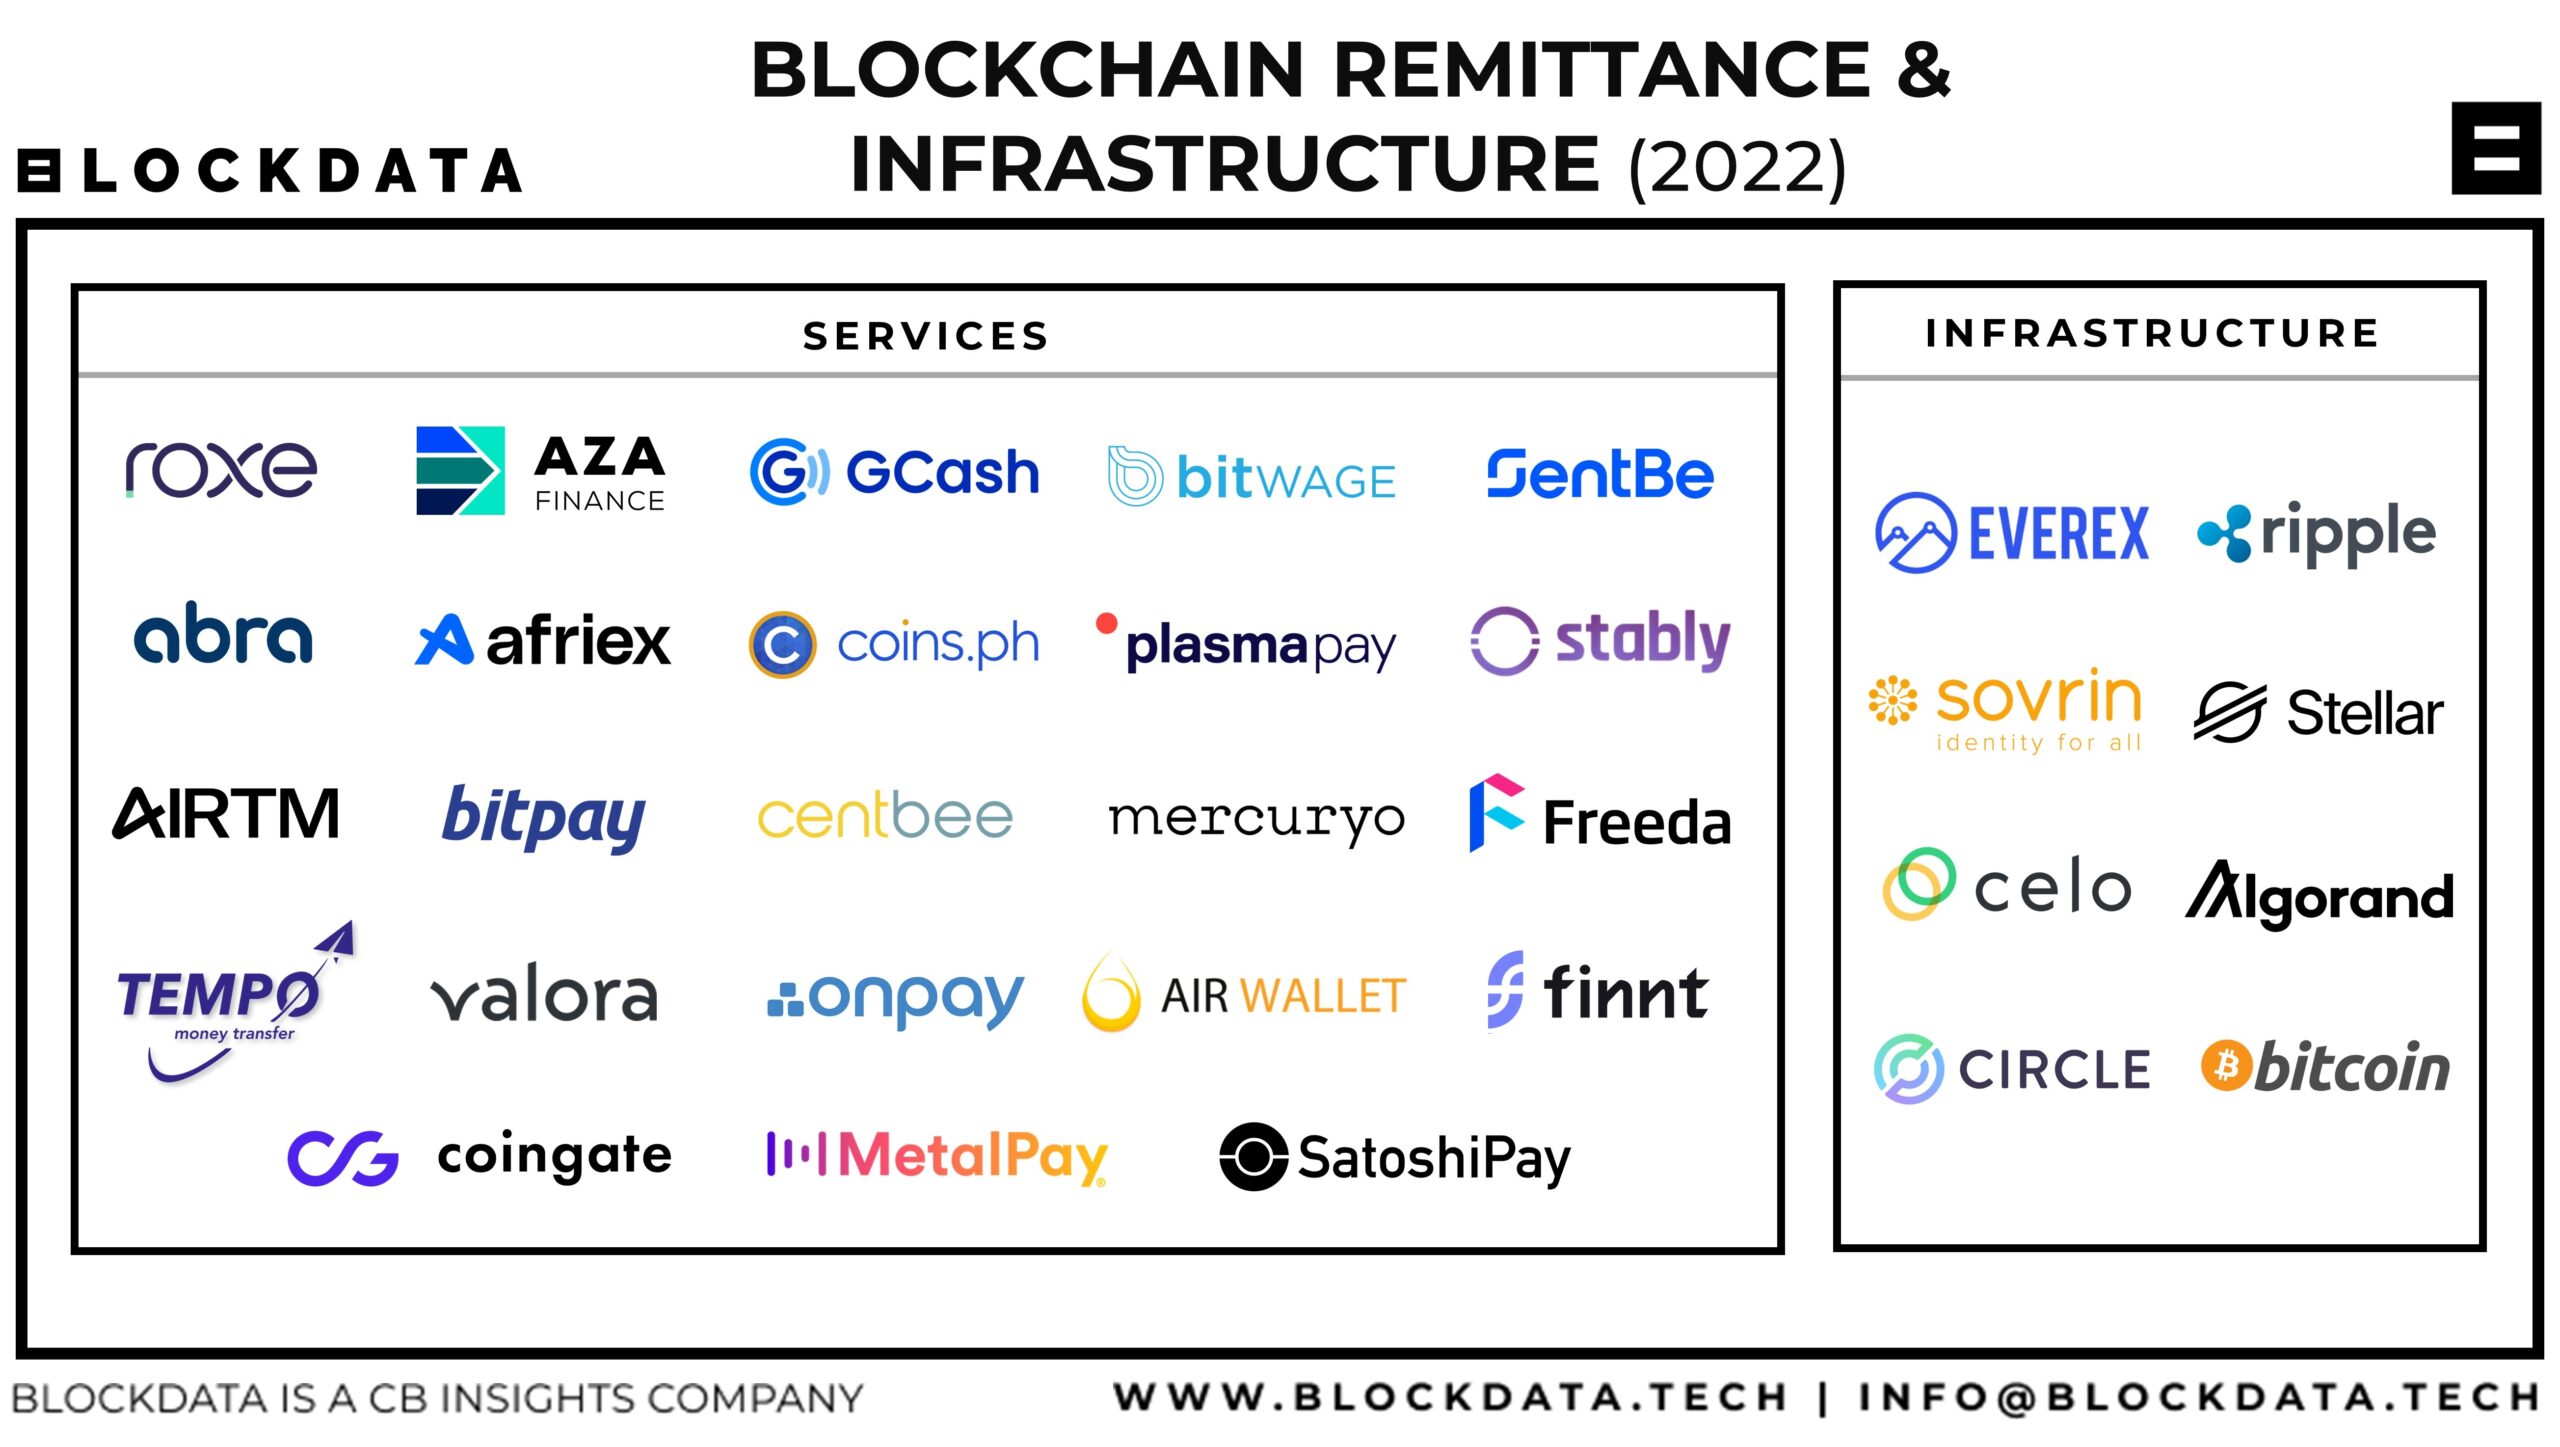
After more than a decade of pilots, crypto has not displaced conventional consumer remittance rails at a meaningful, independently verified scale. Stablecoins have nevertheless become a credible back-end option in select corridors and a useful instrument for digital-dollar access, treasury mobility, and certain high-friction cross-border flows. Most disclosed consumer-remittance implementations remain selective routes, subsidized programs, or company-reported deployments whose scale and unit economics are not independently verifiable.
The decisive question is therefore whether the full end-to-end system, including funding, FX, compliance, liquidity, payout, cash-out, support, fraud, and reversibility, beats modern fiat alternatives on price, speed, reliability, and scale. Public evidence remains strongest for digital-dollar access and some business or treasury use cases, and weakest for broad consumer-remittance transformation.
By 2025, stablecoins had moved from fringe remittance experiments into the product roadmaps of major consumer money-transfer providers. Western Union, Euronet, MoneyGram, Majority and Remitly announced stablecoin wallets, on- and off-ramps, disbursement capabilities or integrations into their existing cross-border networks. This marked an institutional turning point, although in 2025 it still mostly measured announced capabilities rather than consumer usage or transfer volume.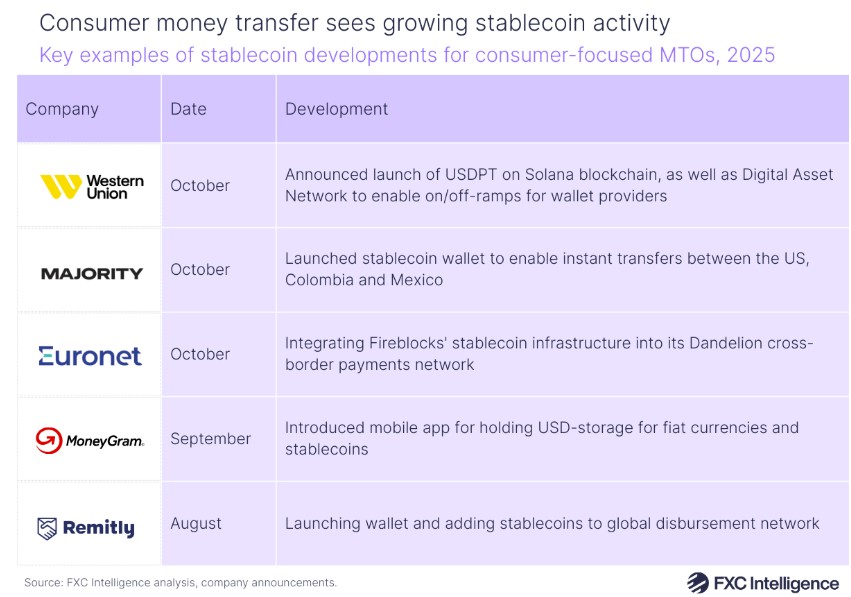
By mid-2026, several of those roadmaps had moved into production. Euronet launched stablecoin payouts; Western Union launched USDPT and Stablecard, with the latter live in 37 markets; MoneyGram launched MGUSD; and Remitly launched a stablecoin card and wallet in selected Latin American markets. This is stronger evidence of institutional adoption than the 2025 announcements. But the cited disclosures still do not quantify how much consumer-remittance volume actually uses stablecoin settlement or demonstrate a reduction in customers’ total fees and FX markup.
MoneyGram does disclose one measure of internal scale: its stablecoin FX trading runs at roughly $2 billion annualized. But that is treasury and FX activity, not disclosed consumer-remittance settlement volume or evidence of lower customer prices.
PYUSD provides an even cleaner warning against treating stablecoin circulation as payment adoption. Its first major boom came after PayPal launched on Solana in 2024, and PYUSD paid roughly 15–18% yields on Kamino and Drift; circulation crossed $1 billion, then fell sharply as those incentives faded. The pattern repeated at much larger scale in 2026. Around PYUSD’s $4.1 billion peak, Ethena alone held $1.13 billion and Aave about $445 million. PayPal then expanded PYUSD availability to 70 markets, explicitly promoting cross-border transfers and dollar access, yet circulation subsequently fell by roughly $1.3 billion as those large DeFi positions unwound.
A more revealing comparison is how leading digital remittance players actually reached scale. Wise and Remitly became global consumer remittance leaders by improving the entire P2P proposition: digital customer acquisition, bank funding, compliance, FX, risk management, and local payouts. They reached that scale before adding stablecoins, if they added them at all. Even in Africa, where stablecoins supposedly rule, Zepz (WorldRemit + Sendwave) and LemFi became two of the continent’s largest digital remittance players before adopting stablecoin infrastructure.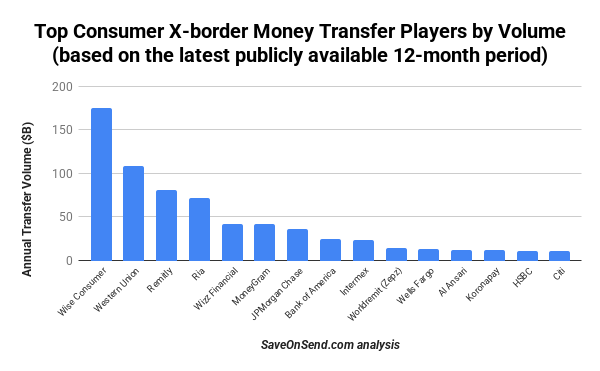
Innovation Adoption: 3 Cases
Stablecoins do not need to replace every remittance rail to become material. They need to win decisively in at least one of three ways: solve a customer problem incumbents leave unresolved, support a business model incumbents cannot match, or create new transfer demand. The rest of this article tests each path.